Mergers & Acquisitions
Buying, owning and expanding a business internationally
Advice on, and introductions to, M&A opportunities and the acquisition or ownership of operating businesses in international markets, including restaurants, hotels, nail salons, spas, shops and other types of business. For investors who want to combine a business investment with a residence or settlement plan, Wobridge works with legal specialists and local partners to build a structure that fits local rules.
- Transaction readiness
- Due diligence preparation
- Data-room organisation
- Cross-border coordination
Market
Choose the market you are looking at
See M&A articles and opportunities by country. Each market has its own rules and practice, so Wobridge prepares the work to the requirements of the country you choose.
What preparation involves
A transaction is easier to run when the groundwork is done first
Most of the effort in a transaction is spent answering questions — from a counterparty, from advisers and from your own board. Preparation means having clear answers before the questions arrive.
Mergers and acquisitions cover a wide range of situations: selling a business or part of it, acquiring another company, combining two businesses, forming a joint venture or bringing in a strategic investor. Each has its own legal, tax and commercial questions, and in a cross-border transaction those questions arise separately in each jurisdiction involved.
What most transactions have in common is the work around them. Someone has to decide what the transaction is for. Someone has to gather and explain information about the business. Someone has to make sure that lawyers, accountants, tax advisers and other specialists know what the others are doing. When that work is left until a counterparty is already asking, it is done under pressure and often more than once.
Wobridge works on that preparation and coordination. We help a business structure its thinking, organise its information and frame the questions that need answering. Legal questions — transaction structure, contracts, international investment matters and disputes — are handled by Wobridge's lawyers within their areas of expertise, coordinating with partner lawyers in each jurisdiction where local advice is needed. We do not act as an investment bank, broker, auditor, accountant, tax adviser or valuer, and we never present ourselves as one.
Where Wobridge helps
- Clarifying and writing down the objective of a possible transaction
- Building a clear profile of the business and its ownership
- Organising corporate, commercial, financial and people information
- Identifying information gaps before others find them
- Preparing for due diligence and structuring a data room
- Tracking questions, answers and open issues across advisers
- Coordinating communication between specialists in several countries
What Wobridge does not do
- Give tax, accounting or regulated investment advice
- Value a business or recommend a price
- Find buyers, sellers or investors, or act as a broker
- Negotiate or sign transaction documents on your behalf
- Promise that a transaction will happen or on what terms
Who may consider a transaction
Situations where preparation tends to matter
Transactions start for many reasons. The preparation is similar even when the circumstances are very different.
Owners planning a sale or succession
Founders and families considering selling all or part of a business, or planning how ownership will pass to the next generation or to management.
Businesses looking to acquire
Companies considering buying another business to enter a market, gain a capability or secure a supply chain, and wanting to approach it methodically.
Companies entering a new market
Businesses weighing a partnership, joint venture or acquisition as a way to establish themselves in another country.
Businesses bringing in an investor
Owners considering a strategic or minority investor and wanting their information, governance and objectives to be clear first.
Businesses considering a combination
Two companies exploring whether to come together, and needing to understand each other before committing to anything.
Groups reorganising their structure
Groups moving activities, assets or people between entities, often as a step towards another transaction.
None of these situations is a qualification test. If a transaction is being considered at all, the same preparation questions apply.
Clarify the objective
Start with what the transaction is for
The most useful document in early preparation is usually the shortest: a one-page statement of what the business wants to achieve.
Transactions are often discussed in terms of a counterparty or a headline price. Both are poor starting points. A clear objective comes first, because it decides which kind of transaction makes sense, which advisers are needed, what they should look at and which opportunities should be declined.
A good objective statement names the kind of transaction being considered, why now, what success would look like, the conditions the business will not trade away and the point at which it would walk away. It is not a legal document; it is the brief every adviser works from.
Selling all or part of the business
Transferring ownership to a buyer, with attention to people, continuity and the obligations that remain afterwards.
Acquiring a business
Bringing another business, or some of its activities, under your control, with a clear view of what you would be taking on.
Strategic partnership
Working closely with another business by contract, keeping separate ownership while sharing a defined goal.
Market entry
Using a transaction as a way into a new market, where local knowledge, relationships and presence matter.
Business combination
Bringing two businesses together, where governance, culture and integration weigh as much as the terms.
Succession-related planning
Planning how ownership or control will change as founders step back, alongside family and management considerations.
Portfolio reorganisation
Reshaping a group by moving, separating or combining activities before or alongside another step.
These are descriptions of business goals, not a list of regulated services. Which forms are available, and what each involves, is for qualified advisers to explain in your circumstances.
Seller readiness
Help others understand your business accurately
A buyer or investor can only assess what they can understand. Seller readiness is about making the business understandable — not about presenting it favourably.
Most of the information a buyer will ask about already exists somewhere inside the business. The work is to find it, organise it, check that it is consistent and add the context an outsider needs. Done early, this lets the business find and address its own issues before someone else raises them.
The business story
A clear account of what the business does, how it makes money, what makes it distinctive and how it has developed.
Ownership and corporate structure
Which entities exist, who owns them, how ownership has changed and who holds management and signing authority.
Financial information
Historical statements, management reports and an explanation of how figures are defined and reconciled.
Significant contracts
Key customer, supplier, partner and property arrangements, including any that could be affected by a change of ownership.
Customers and suppliers
Who the most important relationships are with, and how dependent the business is on any of them.
People and organisation
The organisation, key roles and the general basis on which people work, prepared first at an aggregated level.
Key operational dependencies
Sites, systems, suppliers or individuals the business could not easily operate without.
Intellectual property and documentation
What the business has created or relies on, and how that is recorded and protected — concepts to confirm with counsel.
Management information
The reports management actually uses to run the business, and what they show.
A simple risk register
Known issues, disputes, weaknesses and open questions, written down honestly with an owner for each.
This is a way of organising preparation, not a list of what any law requires a seller to disclose. Disclosure obligations are a matter for your lawyers.
Buyer readiness
Know what you are looking for before you start looking
A buyer that has clarified its own position makes better use of the information it receives and asks better questions of it.
Strategic rationale
Why an acquisition, and why now? What should the combined business be able to do that neither can do alone?
Target criteria
The characteristics a suitable target should have — activity, size of operation, location, culture — and those that would rule one out.
Decision authority
Who inside the business can decide to proceed, to commit resources and to stop, and how quickly they can be reached.
Funding discussions
How a transaction might be funded is a question for appropriate financial professionals; identifying who to speak to belongs in early preparation.
Information-request planning
What you will need to know about a target, in what order, and which questions matter most to the decision.
Due-diligence scope
Which areas need review for this transaction, and which specialists should review them, agreed with your advisers.
Deal-team roles
Who leads, who coordinates, who answers internal questions and who speaks to the other side.
An integration hypothesis
An early view of how the target would be run afterwards, so that review work tests the assumptions that matter.
Wobridge does not give financing or investment advice. We help a buyer organise its thinking and its questions so that the right professionals can answer them.
Business information readiness
The information that explains how the business works
Beyond documents, counterparties want to understand the business model and its dependencies. These themes help organise that explanation.
Business model documentation
How the business creates and delivers value, written plainly enough for an outsider to follow.
Ownership structure mapping
A chart of every relevant entity and owner, checked against the underlying records.
Management information
The regular reports used to run the business, with notes on what each measures and how.
Customer and supplier concentration
Whether a significant share of activity depends on a few relationships, described in words rather than as figures.
Operational risks
What could interrupt the business — a key person, a system, a site, a supplier — and how it is managed.
Compliance overview
Which rules the business believes apply to its activities and how it manages them, to be reviewed by qualified advisers.
Financial-information preparation
Organise the numbers so they can be explained
Financial information is reviewed closely in almost every transaction. Preparation is about having it organised, consistent and explainable — not about interpreting it.
Historical financial statements
The formal statements for the periods your accountants recommend, in one place.
Management reports
Internal reports and how they reconcile with the formal statements.
Revenue categories
How revenue is grouped — by product, customer type, channel or location — and why.
Cost categories
How costs are classified, and which are fixed, variable or related to particular activities.
Working-capital information
Receivables, payables and inventory, and how they move during the year.
Debt and other obligations
Borrowings, security given for the obligations of others, leases and other commitments that a counterparty will want to understand.
Forecast assumptions
If forecasts are shared, the assumptions behind them, stated clearly and separately from the numbers.
One-off items
Unusual events that affected results, with an explanation and supporting records.
Financial definitions
What terms such as revenue, margin or profit mean in each report, so that nobody compares unlike with unlike.
Due-diligence preparation
Prepare for the review before it begins
Due diligence is a structured review of a business by the other side and its advisers. It runs in several workstreams at once, and each draws on information you can organise in advance.
The specific scope of any review depends on the transaction, the sector, the jurisdictions involved and the advice of qualified professionals. The workstreams below are common areas of focus, described so that preparation can be organised around them — not a statement of what any review will or must cover.
A business that has prepared can answer requests quickly and consistently, find its own issues first and keep control over what is shared and when. A business that has not tends to answer the same question several times, in slightly different ways.
Commercial
Markets, customers, competitive position and the assumptions behind the business plan.
Financial
Quality and consistency of financial information, working capital and obligations.
Legal
Corporate records, ownership, significant contracts, disputes and regulatory matters, reviewed by qualified lawyers.
Tax
The tax position of the business and the consequences of the transaction, reviewed by qualified tax advisers.
Operational
Sites, processes, suppliers and the practical dependencies of running the business.
Technology
Key systems, software, data and how they are maintained and supported.
Cybersecurity
How systems and data are protected and how incidents have been handled.
HR and people
Organisation, key roles, terms of engagement and people-related issues.
Environmental and regulatory, where relevant
Permits, sites and sector rules, where the activities of the business make them significant.
Which workstreams apply, how deep each goes and who carries it out are decided with qualified advisers for each transaction.
Data-room organisation
One structured place for the information that is shared
A data room — usually a secure online space — is where information is made available to a counterparty and its advisers. Its usefulness depends on the discipline behind it.
Folder structure
Folders that follow the themes of the review, mirroring the internal index so that every document has one obvious place.
Version control
One current version of each document, older versions archived, and a note of what changed and why.
Access discipline
Access granted by folder and by stage, to the people who need it, and reviewed as the process moves on.
Document naming
Consistent names and stable references, so that questions and answers can point to the right file.
Question tracking
Every question logged with an owner, a status and the answer given, so that answers stay consistent.
Missing-document log
An honest record of what is not available yet, why, and when it is expected.
Responsibility ownership
A named internal owner for each area, who checks documents before they are released.
Redaction and staged release
Sensitive information held back, masked or released later, on legal advice, as the counterparty's seriousness becomes clear.
A well-organised data room supports a process; it does not decide what must legally be disclosed. That is a question for your lawyers.
Confidentiality
Decide who knows what, and when
A possible transaction is sensitive for employees, customers, suppliers and competitors alike. Confidentiality is planned, not assumed.
Need-to-know access
A small, named circle inside the business, widened deliberately as the process develops.
Document-sharing discipline
Information shared through agreed channels only, with a record of what was sent to whom.
Confidentiality agreements
Commonly put in place before detailed information is exchanged; their terms are a matter for your lawyers.
Sensitive categories
Customer details, pricing, personal data about employees and trade secrets handled with particular care.
Internal communication
A plan for when and how employees will be told, and how a leak would be handled.
Transaction structure concepts
Forms a transaction can take
Transactions are usually described in a few broad forms. Knowing the vocabulary helps a business take part in structuring discussions — the choice itself belongs with qualified advisers.
Share transaction
An ownership interest in a company changes hands, and the company continues with its history and obligations.
Asset transaction
Particular assets, activities, contracts or people are transferred, rather than the company that holds them.
Merger or business combination
Two businesses come together into one group or one entity, by one of several possible routes.
Strategic investment
An investor takes a share in a business, with or without influence over how it is run.
Joint venture
Two or more parties create a shared arrangement for a defined purpose and agree how it is governed.
These are conceptual descriptions only. How each form works, its legal and tax consequences in each jurisdiction, and whether it suits your objective must be confirmed with qualified lawyers and tax advisers. No form is better in general.
Valuation — handled carefully
What value discussions usually consider
Every transaction involves a discussion about value. Understanding what that discussion tends to draw on helps a business prepare the right information — without trying to put a number on it.
Financial performance
How the business has performed, and how reliably that performance can be explained.
Growth expectations
What the business expects to achieve, and how well the assumptions are supported.
Risk
What could go wrong, how likely it is and how it is managed.
Market context
Conditions in the sector and the wider economy at the time of the transaction.
Asset base
What the business owns or controls, tangible and intangible.
Cash generation
How the business converts its activity into cash over time.
Strategic considerations
What the business would mean to a particular counterparty, which can differ from one counterparty to another.
Advisers and the deal team
The specialists a transaction may involve
Which specialists are needed depends on the transaction. Each keeps their own scope; coordination makes sure their work fits together.
Lawyers
Corporate, commercial and other legal advice, with qualified counsel in each relevant jurisdiction.
Accountants
Preparation and review of financial information and its consistency.
Tax advisers
The tax consequences of the transaction and its steps, for each party and in each place.
Financial advisers
Strategic and process support, within the scope of their role and authorisation.
Valuation specialists
An independent, professional view of value based on the information available.
Technical advisers
Assessment of sites, equipment, engineering or operational matters, where relevant.
HR specialists
Organisation, terms, communication and change, including any relocation of people.
Cybersecurity specialists
Review of systems and data protection where technology is central to the business.
Wobridge's role is preparation and coordination: a shared brief for every adviser, an issues list and a question log, a clear record of who is doing what, and questions routed to the right professional. The advice itself always comes from qualified specialists.
How we work
The Wobridge preparation workflow
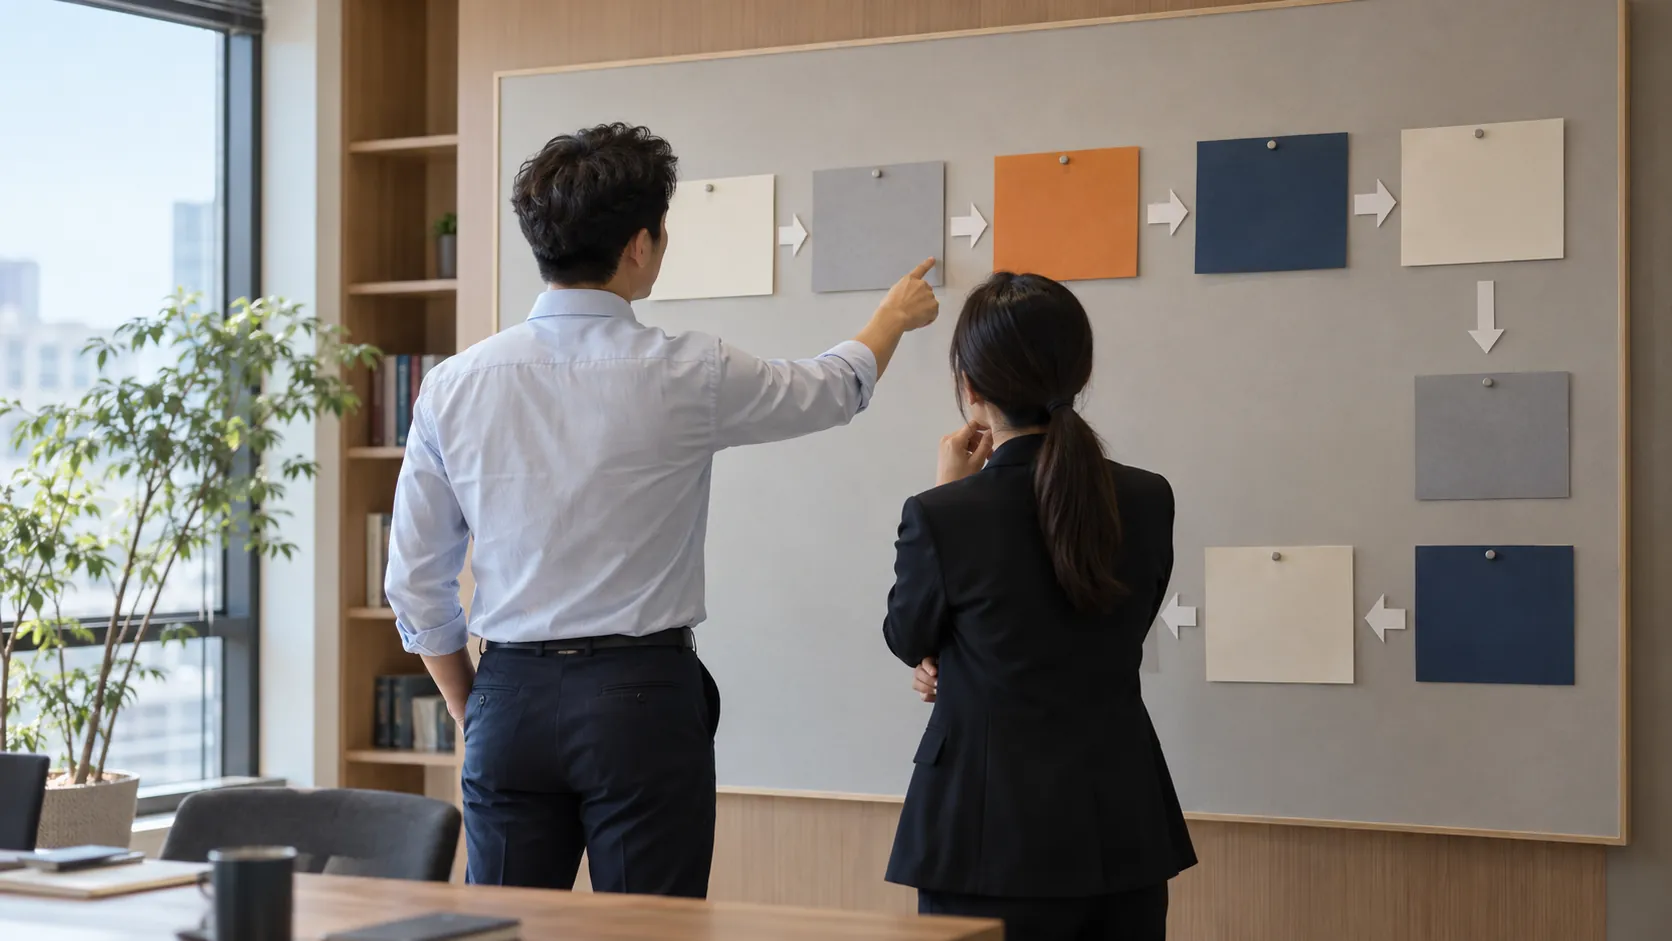
A practical sequence for getting a business ready for transaction discussions. Steps overlap, and some are revisited as things become clearer.
Transparent information – Clear costs – Consistent at every step.
Define the transaction objective
Agree what the transaction is for, what success means, the non-negotiables and the walk-away points.
Build the company and transaction profile
Summarise the business, its ownership and the transaction being considered in a form advisers can work from.
Map stakeholders and advisers
Identify decision-makers, internal owners and the specialists the transaction is likely to need.
Organise core information
Gather corporate, commercial, financial, people and operational information behind a single index.
Identify information gaps
Record what is missing, inconsistent or unclear, with an owner and a plan for each.
Prepare due-diligence materials
Shape the organised information around the workstreams a review is likely to cover.
Structure the data-room workflow
Set up folders, naming, access stages, a question log and a missing-document log.
Coordinate key questions
Route legal, tax, financial and other questions to the right professionals and track the answers.
Prepare next actions
Summarise what is ready, what is open and what the decision-makers need to decide next.
This is how Wobridge organises preparation. The legal steps of any transaction, their order and the approvals they may need are defined for each case by the lawyers handling it — Wobridge's lawyers, with partner lawyers in each jurisdiction concerned.
Common risks and mistakes
Where preparation often falls short
None of these makes a transaction fail on its own. Each can create risk, delay or confusion that preparation could have reduced.
Unclear objectives
Without an agreed objective, every new opportunity or proposal reopens the basic question of what the business wants.
Poor document control
Several versions of the same document in circulation lead to inconsistent answers and lost time.
Inconsistent financial definitions
Reports that use the same word for different things can make the business look less reliable than it is.
Incomplete ownership information
Gaps between the ownership chart, the records and what people believe can slow everything else down.
Information shared too early
Sensitive information released before confidentiality and seriousness are established is hard to take back.
Weak question tracking
Questions answered informally, by different people, in different ways, create confusion later.
Single-person dependency
When one person holds all the knowledge, the transaction and the business both slow down when they are unavailable.
Customer concentration not understood
Reliance on a few relationships that has not been described and explained invites difficult questions late in the process.
Integration ignored until late
Agreeing terms without asking how the combined business will run leaves the hardest questions for after signing.
Uncoordinated advisers
Specialists working from different facts or without sight of each other's work leave questions that nobody answers.
Verify what applies
Transaction-specific requirements come from qualified sources
Every transaction raises questions that only qualified professionals and official sources can answer for your case. This page deliberately does not answer them.
Areas to verify for your transaction
Corporate law
How ownership or control can change hands, and what internal approvals are needed, in each jurisdiction.
Tax
The consequences of the structure and each of its steps, for each party and in each place.
Competition
Whether any competition review or notification could apply to the transaction.
Foreign investment
Whether any foreign-investment screening, approval or restriction could apply in the relevant sector and place.
Licensing
Whether licences or permits held by the business are affected by a change of ownership or control.
Employment
Obligations towards employees, including any duty to inform or consult, and the effect on terms.
Data and privacy
Rules on sharing personal data during the process and on combining data afterwards.
Sector regulation
Rules specific to the industry the business operates in.
Where reliable answers come from
When information conflicts, rely on the higher source and record where each answer came from and when.
Official legislation and regulator publications
The law and official guidance of each jurisdiction, as published by the authority responsible.
Written advice from qualified professionals
Lawyers, tax advisers and accountants qualified in the relevant jurisdiction, applying the rules to your facts.
Recognised professional bodies
Guidance from professional and industry bodies, useful for context but not a substitute for advice.
Secondary commentary
Articles, summaries and conversations — useful for questions, never for answers.
Wobridge helps you prepare the questions and keep the answers organised. It does not supply the answers.
Questions
Frequently asked questions
Short answers to common questions. Where the honest answer is "it depends", we say what it depends on.
What is M&A?
Mergers and acquisitions is a broad term for transactions that change who owns or controls a business: selling it, buying another one, combining two businesses, or forming a joint venture or strategic investment. Each form raises its own legal, tax and commercial questions.
Does Wobridge value businesses?
No. Wobridge does not issue valuations, suggest prices or apply valuation formulas. We help organise the information that qualified financial advisers and valuation specialists need to form a professional view.
What should a seller prepare first?
A clear objective, an accurate ownership chart and an organised set of core information — corporate, commercial, financial and people — behind a single index. Recording gaps honestly matters as much as gathering documents.
What should a buyer clarify first?
Why it wants to acquire, what a suitable target looks like, who can make decisions and which questions matter most. Funding discussions belong with appropriate financial professionals.
What is due diligence?
A structured review of a business by a counterparty and its advisers, usually across commercial, financial, legal, tax, operational and other workstreams. Its scope depends on the transaction and is set with qualified advisers.
What is a data room?
A controlled space, usually online, where information is shared with a counterparty and its advisers. A good one has a clear structure, version control, staged access and a log of questions and answers.
What information usually needs organising?
Typically corporate and ownership records, significant contracts, financial information, people and organisation, operations, technology and known risks. The exact list depends on the business and the review.
When should lawyers and accountants be involved?
Earlier than many owners expect — ideally once an objective is clear and before anything binding is discussed or signed. Early involvement lets advisers raise issues while there is still room to address them.
How long does an M&A transaction take?
It depends on the transaction, the parties, the information available and any approvals or consents that apply. Preparation can remove avoidable delays, but nobody can responsibly promise a timetable in advance; your advisers can explain the factors in your case.
Can a transaction be kept confidential?
Confidentiality can be planned through need-to-know access, staged sharing and confidentiality agreements drafted by lawyers. It cannot be absolute, so plans should include how employees and others will be informed at the right time.
What should I prepare before speaking with Wobridge?
A short description of the business and its ownership, what you are considering and why, any deadlines or constraints, and the advisers already involved. Nothing needs to be perfect — identifying what is missing is part of the work.
M&A insights
Articles on preparing for a transaction
Practical guides on objectives, specialists, due diligence, workstreams, structure questions, people and integration.
Defining the transaction objective before engaging advisers
Buying, selling, combining, partnering and reorganising are different transactions with different work behind them. Why a written objective comes first, and how it shapes scope, structure and the advisers you need.
Read article
Who does what in a cross-border deal: mapping the specialists
A cross-border transaction draws on lawyers, tax advisers, accountants, valuation and technical specialists — often in more than one country. What each role covers, where the gaps between them appear, and what coordination can and cannot do.
Read article
Preparing for due diligence: organising company information
Due diligence goes more smoothly when the business has already gathered its own information. How to build a single index of corporate, commercial, financial and people records, keep versions under control and decide what can be shared, and when.
Read article
Keeping parallel workstreams aligned across jurisdictions
Legal, financial, tax, commercial and people workstreams run at the same time and depend on each other. Practical ways to map dependencies, keep one issues list and one question log, handle language and time zones, and make decisions at the right moment.
Read article
Questions to ask your lawyers and tax advisers before structuring a deal
How a transaction is structured is a question for qualified lawyers and tax advisers in every jurisdiction involved. A question list to bring to them — about share and asset approaches, consequences in each place, approvals, people, and future flexibility.
Read article
Joint venture, acquisition or partnership: framing the decision
Entering a market or working with a foreign party can take several forms, from a commercial partnership to a full acquisition. A business-level framework for comparing them on control, capital, risk, people and how easily each can be unwound.
Read article
Start preparing
Talk to Wobridge about getting ready for a transaction
Tell us what you are considering. We will help you organise the objective, the information and the questions — and keep your qualified advisers working from the same picture.